Whether you're leaving your family a huge chunk of change or you're simply trying to break the "shirtsleeves to shirtsleeves" cycle, the importance of a sound legacy plan is undeniable. Here's what you need to know — and how to get there.
As you enter into your golden years, life may feel busier than ever. Between work life, personal life, family and friends, it seems there’s little time to consider the future. As each season blends into the next, before you know it, another year has passed — another year without securing a proper financial plan for your future.
It’s normal to feel uneasy about your legacy, but experts recommend tackling it head-on.
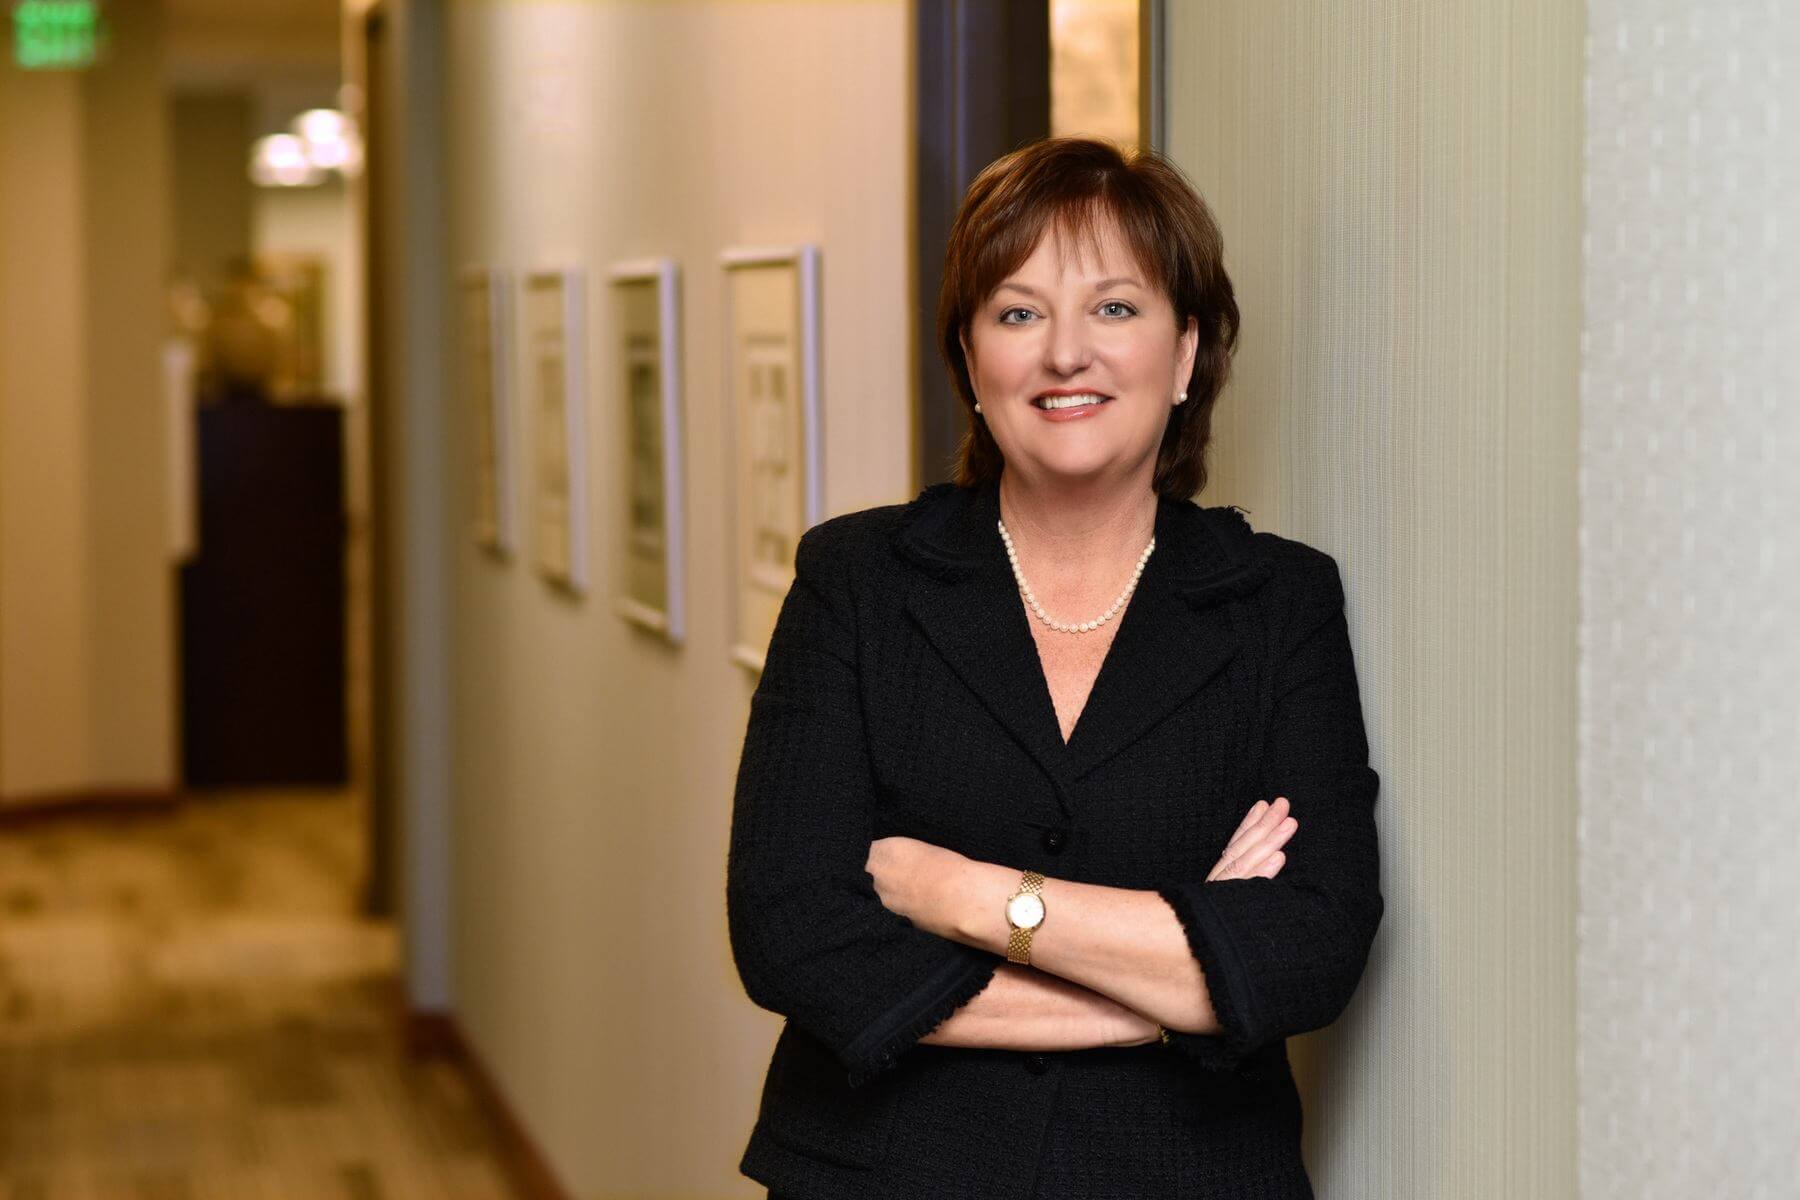
“Not having an estate plan causes a lot of stress,” says Phoebe Venable, CFA®, President and Chief Operating Officer of CapWealth in Franklin. “It’s like other aspects of your health.”
We tapped Phoebe’s expertise to learn more about legacy planning, the reasons why it matters and how not having a plan can impact your future.
PinPhoebe Venable, CFA®, President and Chief Operating Officer of CapWealth in Franklin. Image: Peyton Hoge
7 Legitimate Reasons You Need a Legacy Plan
Estate planning mistakes are expensive.
“The biggest mistake you can make is not having a plan,” Phoebe warns. For starters, when someone dies without a will in the state of Tennessee, it creates a major problem for those left behind. If you don’t have a will, the state decides where your assets go, and no matter how much your family swears you wanted things a certain way, your wishes won’t impact their decision.
A good rule of thumb is to revisit your will as your family situation becomes more complex. For example, a simple will may be enough when you first get married, but once you have children, you’ll need to address guardianship. If you pass away, you wouldn’t want the state making guardianship decisions for you, would you?
Another example is if you accumulate enough wealth, you’ll likely need a more in-depth tax strategy. Paying less in federal estate taxes means more money for your family, and there is also a generation-skipping transfer tax to be mindful of. Like any tax strategy, it’s critical to take a proactive approach because unfortunately, there are many types of estate planning errors that can’t be undone.
Another common error is when too much money is left to an irresponsible spender. Having unrestricted access to large amounts of money may not be the right move, but specific trusts or a spendthrift provision can help avoid this. Planning techniques like these can help preserve the wealth you have worked so hard to create.
Major life events may spark action.
It’s common to see families with large amounts of wealth managing their own money. However, certain situations — a career milestone or terminal diagnosis — can often change things. In Phoebe’s practice, major life events like these often spark the need for professional expertise. “These types of events may shift you out of do-it-yourself mode,” she says, underscoring the importance of bringing in a professional before things like this happen.
Your plan won’t work without communication.
Many families make the common mistake of failing to communicate with their children, a problem that, according to Phoebe, crosses all levels of wealth. Once your children are old enough, you should include them in the planning process, sharing exactly how much you own, where the assets are and how you want them dispersed. Having these conversations early and often is the best way to avoid major hiccups later. “There should never be surprises when you pass away,” Phoebe notes. “If there are, you missed planning opportunities.”
Second marriages can be complicated.
Adding a new spouse to the mix? This may complicate things. It may also increase your chances of miscommunication. If your spouse has been around since your kids were very young, there may not be a problem, but if the new significant other is new to the family, your long-time relatives may not appreciate staying bound together by your wealth. In Phoebe’s experience, it doesn’t end well 95 percent of the time.
Experts like Phoebe are well-versed in mixed family dynamics. They anticipate these types of scenarios and can craft a more balanced strategy. There’s no reason for a transfer of wealth to create friction for your family.
Stretching wealth beyond three generations isn’t easy.
Ever heard the proverb “shirtsleeves to shirtsleeves in three generations”? It refers to generational wealth and how it often doesn’t stretch past the grandkids. Replace shirtsleeves with clogs or rice paddies — Phoebe says the same adage rings true around the world.
What it means is this: The first generation often comes from humble beginnings. Without education, they create wealth through entrepreneurship. Their children enjoy the fruits of their parents’ labor by going to college, an opportunity that prepares them to become high-earning professionals. The problem is, the third generation doesn’t appreciate their grandparents’ sacrifice.
“If the family’s values aren’t passed down with wealth, the grandchildren may feel entitled,” explains Phoebe. “In these situations, it’s common for them to spend through all the money.” It’s too easy to spend everything they inherit, sending their own children — the fourth generation — back to working in shirtsleeves like their grandparents.
PinIf the grandkids are entitled, the lifetime you spent accumulating your wealth could be wasted in no time!
Education is the key to lasting wealth.
CapWealth has worked in multi-generational wealth management for years, and their experience has proven that education is the secret to success. Phoebe, who spearheads the company’s efforts of engaging children at a young age, ensures that kids learn about the roles money will and won’t serve in their lives, and that they also learn their responsibility to the family.
“Families who do the work are most successful,” says Phoebe. “They’re able to transfer wealth past the bottleneck we often see at the third generation.”
CapWealth offers a money camp for its clients’ grandchildren ages 6-14, where kids learn money basics like inflation and compounding. They also learn the four ways to use money: spending, charitable giving, saving and investing. They leave knowing why budgeting matters, regardless of how much money their family has.
Always work with a professional.
Legacy planning gives you the chance to assign meaning to your wealth, as YOU can define what it means to your family and how it will benefit generations to come. But stretching it past the third generation doesn’t happen by accident — it’s more than choosing the right set of investments. The plan begins with an open family dialogue, and from there you can craft a customized estate plan based on your values and goals.
Education is the way to make sure these values remain intact, and by working with a financial advisor, you can enjoy the peace of mind that comes along with that.
“You will feel better knowing a professional is watching out for your family’s future,” Phoebe adds. “It becomes a much softer pillow to rest your head on at night.”
To learn more about the financial services offered by CapWealth, visit capwealthgroup.com.This article is sponsored by CapWealth.
Our unofficial motto at StyleBlueprint is "Be kind. Do good." We encourage this to be the basis for all comments on our articles. Provide feedback that adds to the story. Some controversy or disagreements are part of any good dialogue between friends, but anything that tears down or belittles others is subject to disapproval or removal. Thank you for being a member of the StyleBlueprint community! View our Community Guidelines.